Some costs your business really paid in 2026 will still be added back to its taxable profit. The money left the account and the receipt is on file, yet the law does not let you deduct it. Rwanda's income tax law sets four tests that every deductible expense must pass, then names twelve kinds of expense that are not deductible, in full or in part.
If your tax year is the calendar year, the 2026 income tax return is due by 31 March 2027, and RRA has asked taxpayers to record their unsupported expenses on E-Tax before 31 December 2026. Everything below is as at 23 October 2026.
Article 24 of Law No. 027/2022 establishing taxes on income sets the conditions. To be deducted from taxable income, an expense must:
- have been incurred wholly and exclusively for the purpose of business, and be directly chargeable to the income;
- correspond to a real expense that can be substantiated with a proper invoice or receipts accepted by the tax administration;
- lead to a decrease in the net assets of the business;
- have been used for activities related to the tax period in which it was incurred.
A cost with no proper invoice or receipt behind it fails the second test, however real it was.
Article 25 then lists what cannot be deducted: "The following expenses are not deductible from taxable income".
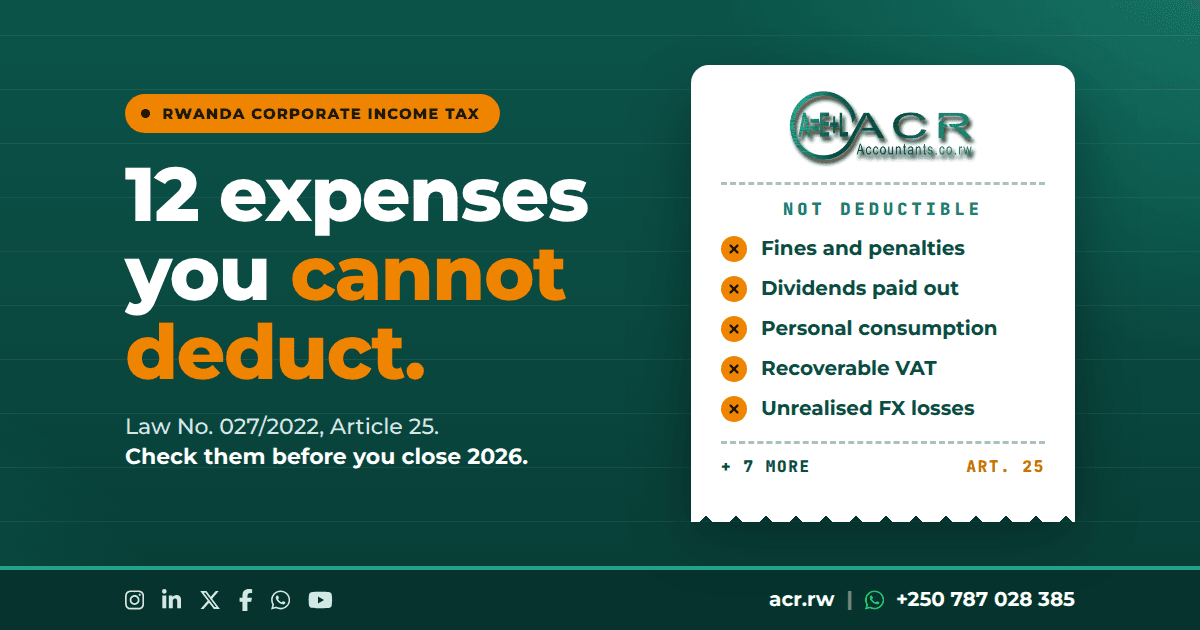
- Dividends declared and profits paid out to their beneficiaries. Sharing profit with the owners is not a cost of earning it.
- Reserve allowances, savings and other special-purpose funds, unless the law provides otherwise. Setting money aside is not spending it.
- Fines and similar penalties. A traffic fine or a tax penalty does not reduce taxable profit.
- Donations, except donations to non-profit making organisations whose value does not exceed 1% of the turnover. On a turnover of RWF 300 million, 1% is RWF 3 million.
- Income tax paid under this law or paid abroad on business profit, and recoverable VAT. VAT you can recover is not a cost to the business.
- Personal consumption expenses. The owner's family shopping or a child's school fees paid from the business account stay personal, whatever the ledger calls them.
- Entertainment expenses, except expenses on general sporting activities for employees. A sports activity organised for the staff is an example.
- Twenty per cent (20%) of expenses paid on business overheads, including telephone, water, electricity and fuel, whose private and business use cannot be practically separated. If the business paid RWF 2,400,000 for fuel for a car the owner also drives at the weekend, and the two uses cannot be split, RWF 480,000 is not deductible. Where you can separate the two with records, keep those records.
- The aggregate of expenses of management activities, technical services and royalty fees paid to a non-resident related person exceeding two percent (2%) of the turnover of the taxpayer. This concerns businesses that pay a related company abroad, such as a foreign parent. On a turnover of RWF 500 million, 2% is RWF 10 million.
- Interest on loans between related persons "paid or due on total loans in excess of four (4) times" the paid-up equity. Paid-up equity here excludes provisions or reserves and retained earnings, according to the balance sheet drawn up under generally accepted accounting principles. On paid-up equity of RWF 50 million, four times is RWF 200 million. This item does not apply to commercial banks, insurance companies and other financial institutions.
- Realised foreign exchange losses arising from total loans between related persons in excess of four times the paid-up equity, using the same definition of paid-up equity.
- Unrealised foreign exchange losses. A loss that exists only because a foreign-currency balance was revalued at year-end, before anything was paid or received, is not deductible.
Article 25 closes with one helpful line: "However, a mandatory contribution paid by a taxpayer is allowed as deductible expense."
Plenty of real business costs never come with an EBM invoice. RRA guidance for 2026, in a taxpayer presentation dated 20 October 2026, asks every taxpayer subject to 2026 income tax to record on E-Tax each business expense that is not supported by an EBM invoice, a customs declaration (DMC) or a withholding tax certificate, so that it can be deducted from 2026 taxable income.
The examples RRA gives include:
- bank and mobile money charges, interest and loan fees, and realised exchange losses;
- purchases from farmers, and from individuals who are not in business;
- missions, charity contributions and claims paid by an insurer;
- services bought and consumed abroad, such as transport and accommodation;
- government fees, parking fees and document fees;
- year-end adjustments such as depreciation, provisions and accruals.
On E-Tax, go to Income tax preparation, select the year, open "Daily Capture of Uncontrolled Expenses" and use Add Transaction to enter expenses one by one. If you have many, RRA's batch upload takes its Excel template together with a zipped folder of the supporting documents. Capture closes on 31 December 2026.
Most taxpayers have not started yet. By RRA's own count, 2,500 of its 42,500 real-regime taxpayers had begun capturing by October 2026, about one in seventeen. RRA also warns against declaring false or inflated expenses. For help, the RRA call centre is 3004 and its WhatsApp line is +250 739 008 010.
Capturing an expense records it. It does not make an expense that Article 25 disallows deductible. RRA's own list of year-end adjustments includes unrealised exchange losses and "penalties and fines to be added back". Charity contributions belong in the capture too, and the 1% limit on donations to non-profit organisations still applies.
- List every 2026 expense that has no EBM invoice, customs declaration or withholding tax certificate, gather the documents and capture them on E-Tax. RRA's advice is not to wait until the last minute.
- Go through the 2026 ledger with Article 25 beside you and mark the add-backs: fines, entertainment, personal costs, donations above the 1% line and 20% of mixed-use overheads.
- If you pay fees or interest to a related company abroad, work out the 2% and four-times limits now, while the year is still open, so March holds no surprises.
ACR-Online Accounting Services keeps the books and prepares tax returns for small and medium businesses in Rwanda. In a year-end tax review we go through your 2026 books with you, mark the expenses Article 25 disallows, help you capture unsupported expenses on E-Tax before the window closes, and prepare your return for March. If your accountant already does this with you, use this article as a checklist together.
Call or WhatsApp us on +250 787 028 385, email info@accountants.co.rw, or visit us in Kimironko, 2 KG 167 St, near Simba Supermarket.
This article is general information as at 23 October 2026. It is not advice for a specific business. Check your own case with RRA or your accountant before you file.
- Law No. 027/2022 of 20/10/2022 establishing taxes on income, Articles 24 and 25, Official Gazette n° Special of 28/10/2022.
- Law No. 051/2023 of 05/09/2023 amending Law No. 027/2022, Article 1 (annual declaration by 31 March), Official Gazette n° Special of 14/09/2023.
- Rwanda Revenue Authority, "Capturing of Unsupported Expenses", taxpayer presentation on 2026 income tax, 20 October 2026.
- Rwanda Revenue Authority, Tax Handbook (2025), page 157 (the E-Tax capture menu).